Useful content begins with a real question
Insurance marketing works better when it answers the questions clients already ask: what a deductible does, why replacement cost matters, what information helps a quote, how beneficiaries work, or when a business should report operational changes. Educational content can demonstrate clarity without promising a product outcome.
Advertising rules still apply
A social post may be short, but it can still be an advertisement. State insurance laws, carrier agreements, agency policies, platform rules, and general advertising standards may apply. The Federal Trade Commission advertising guidance emphasizes truthful, non-misleading claims and clear disclosure of material connections.
Avoid promises and incomplete comparisons
Do not guarantee savings, coverage, eligibility, claim payment, returns, or underwriting outcomes. Explain that rates and availability depend on facts, state, carrier, and contract. Comparisons need a fair basis and material limitations. A dramatic hook is not worth creating a misleading impression.
Protect client privacy
Never use a client story, testimonial, photo, claim, or identifying detail without proper permission and compliance review. Even a story with the name removed may be identifiable in a small community. Do not invite users to post health, policy, claim, or account information in public comments.
Build a balanced calendar
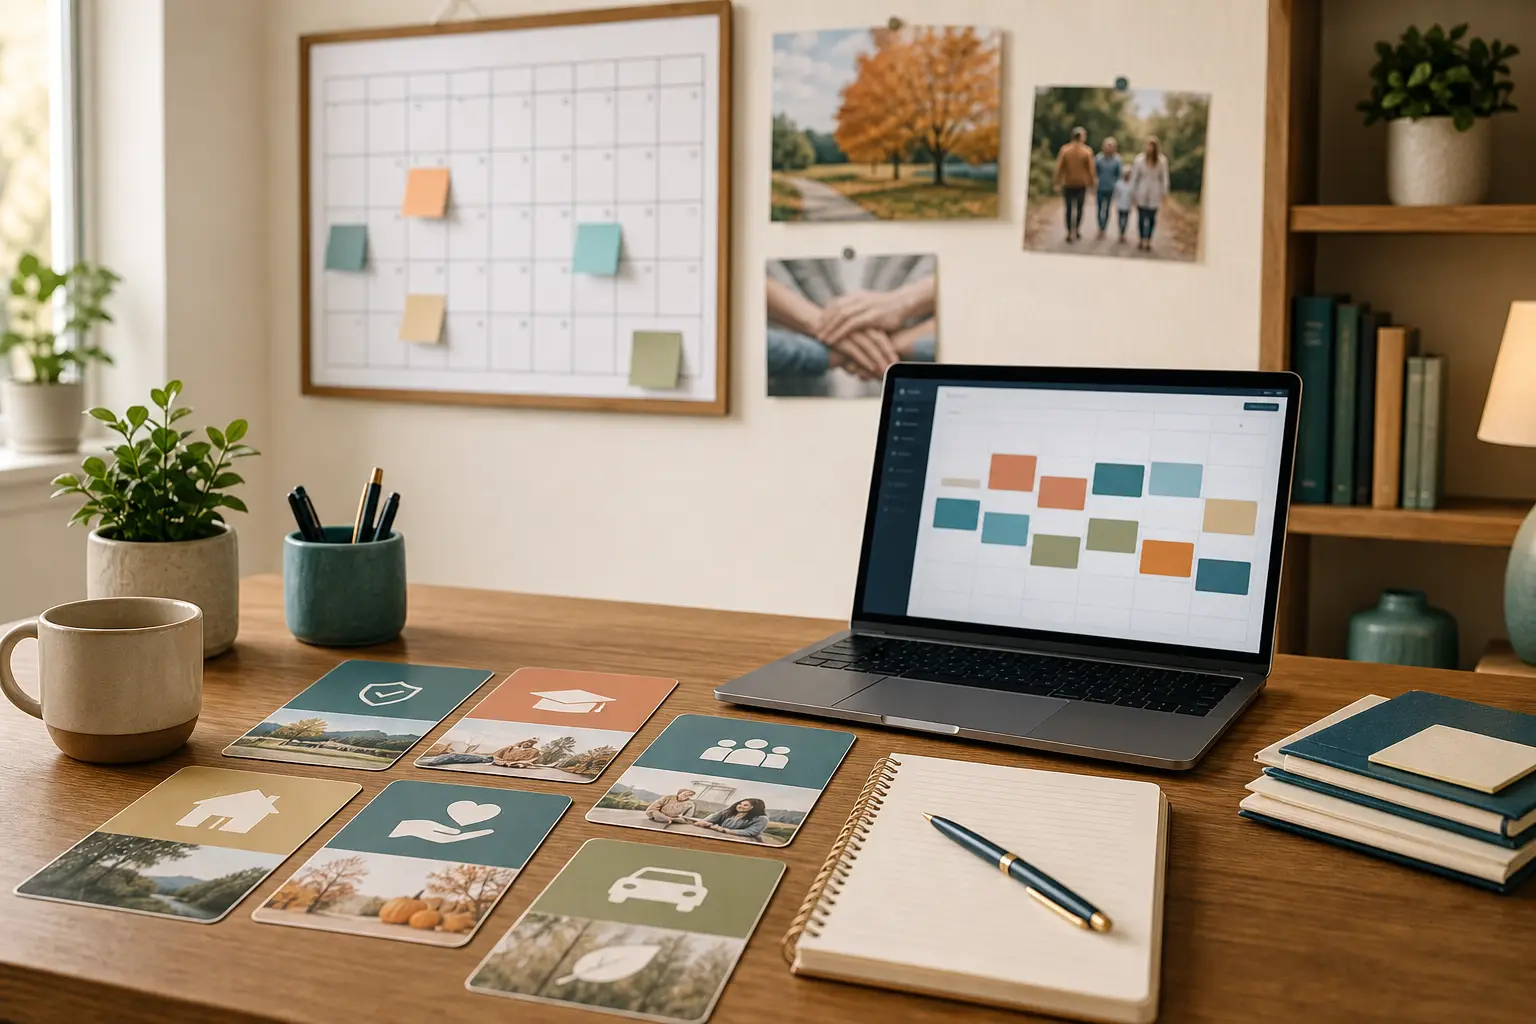
Rotate plain-language education, seasonal preparation, agency process explanations, community involvement, team expertise, and calls to review coverage. Link deeper topics to a sourced article on the agency site. A steady library of useful pages gives social posts somewhere valuable to send the reader.
Review and archive
Use an approval workflow for regulated or product-specific content. Preserve the final copy, image, link, approval, channels, and publication date according to agency policy. Revisit evergreen posts when regulations, products, or linked pages change. Remove or correct content that has become misleading.
Important note: Carrier requirements, policy language, compensation arrangements, licensing rules, and state requirements can change. Use current carrier and regulatory materials, document the source reviewed, and consult appropriately licensed or qualified professionals before acting on a specific situation.